Tag: Complex Numbers

  • Marden’s Theorem: How the Derivative of a Cubic Finds an Ellipse

    What can the derivative of a polynomial tell us about geometry? For a cubic polynomial with three complex roots, the answer is surprisingly precise: the derivative locates the two foci of a particular ellipse.

    Let

    p(z) = (z−z1) (z−z2) (z−z3),

    where z1, z2, z3 are three distinct, noncollinear complex numbers.

    Every complex number can be represented as a point in the complex plane. Therefore the three roots of p become three points, and those three points form a triangle.

    Now differentiate. Since p is cubic, p′(z) is quadratic and has two roots, counted with multiplicity. Call them w1 and w2.

    Where are these two critical points located, and what do they have to do with the triangle formed by the original three roots?
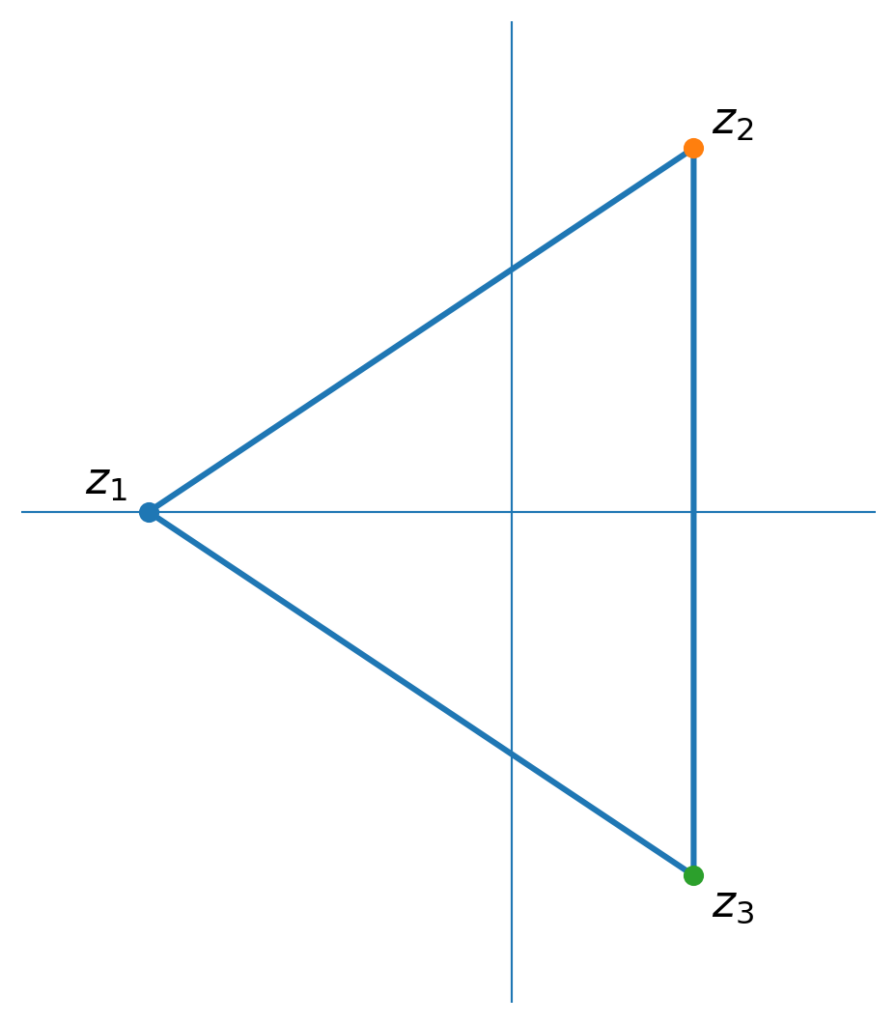
    Three complex roots z1, z2, and z3 plotted as points in the complex plane and joined to form a triangle.
    Figure 1. Three noncollinear roots z₁, z₂, and z₃ of a cubic polynomial determine a triangle in the complex plane.

    What does the derivative know about the triangle?

    There is already a classical theorem that gives us some information. The Gauss–Lucas theorem states that the zeros of the derivative of a polynomial lie in the convex hull of the zeros of the polynomial.

    For our cubic, the convex hull of the three roots is simply the triangle with vertices z1, z2, z3. Therefore the two zeros of p′ must lie inside this triangle.

    That is already an interesting connection between differentiation and geometry. But for a cubic, something much stronger is true.
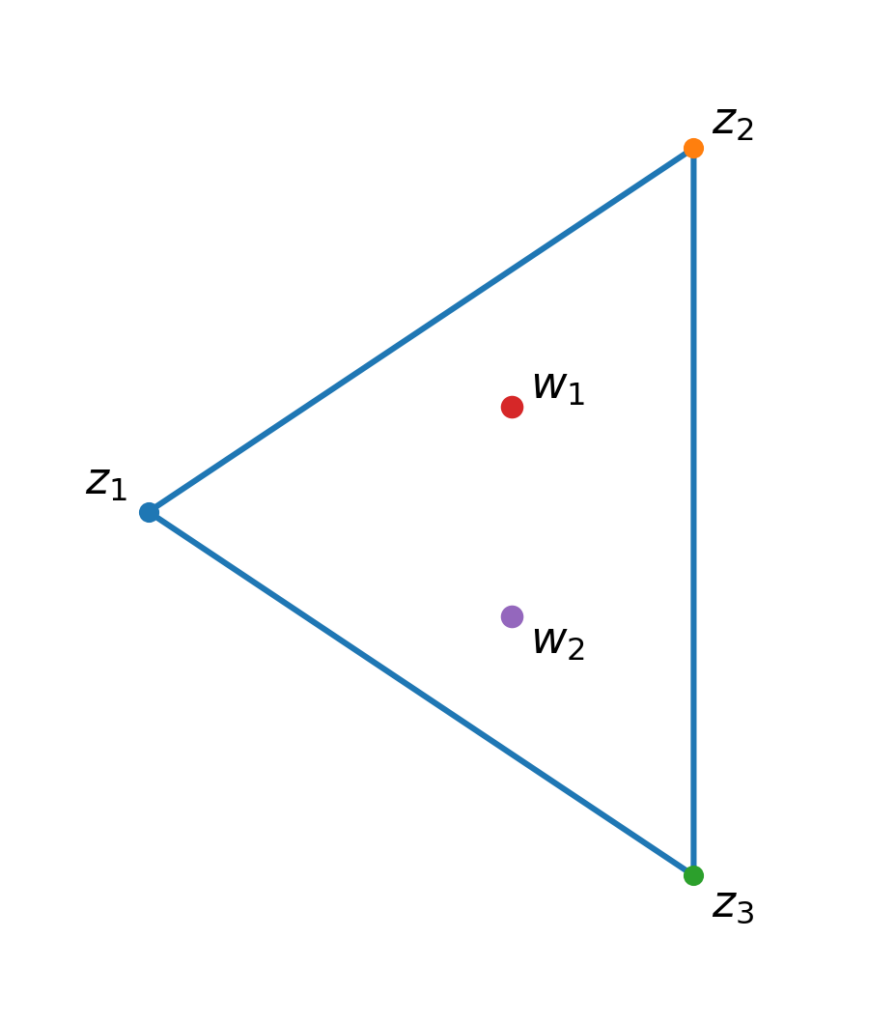
    Triangle formed by three complex roots z1, z2, and z3, with the two derivative zeros w1 and w2 shown inside the triangle.
    Figure 2. By the Gauss–Lucas theorem, the two zeros w₁ and w₂ of the derivative lie inside the triangle determined by the three roots of the cubic.

    Marden’s theorem

    Recall the Steiner inellipse of a triangle: the unique ellipse tangent to the three sides at their midpoints.

    We discussed this ellipse and an area characterization of it in The Steiner Inellipse and a Surprising Area Characterization .

    Marden’s theorem reveals a completely different way in which the same ellipse appears.

    Marden’s Theorem. Let

    p(z) = (z−z1) (z−z2) (z−z3),

    where the three roots are noncollinear. Then the two zeros of p′(z) are exactly the two foci of the Steiner inellipse of the triangle whose vertices are z1, z2, z3.

    This is much stronger than Gauss–Lucas. Gauss–Lucas tells us that the critical points are somewhere inside the triangle. Marden’s theorem identifies their exact geometric meaning.

    The derivative of the cubic has found the foci of an ellipse determined by the roots of the original polynomial.
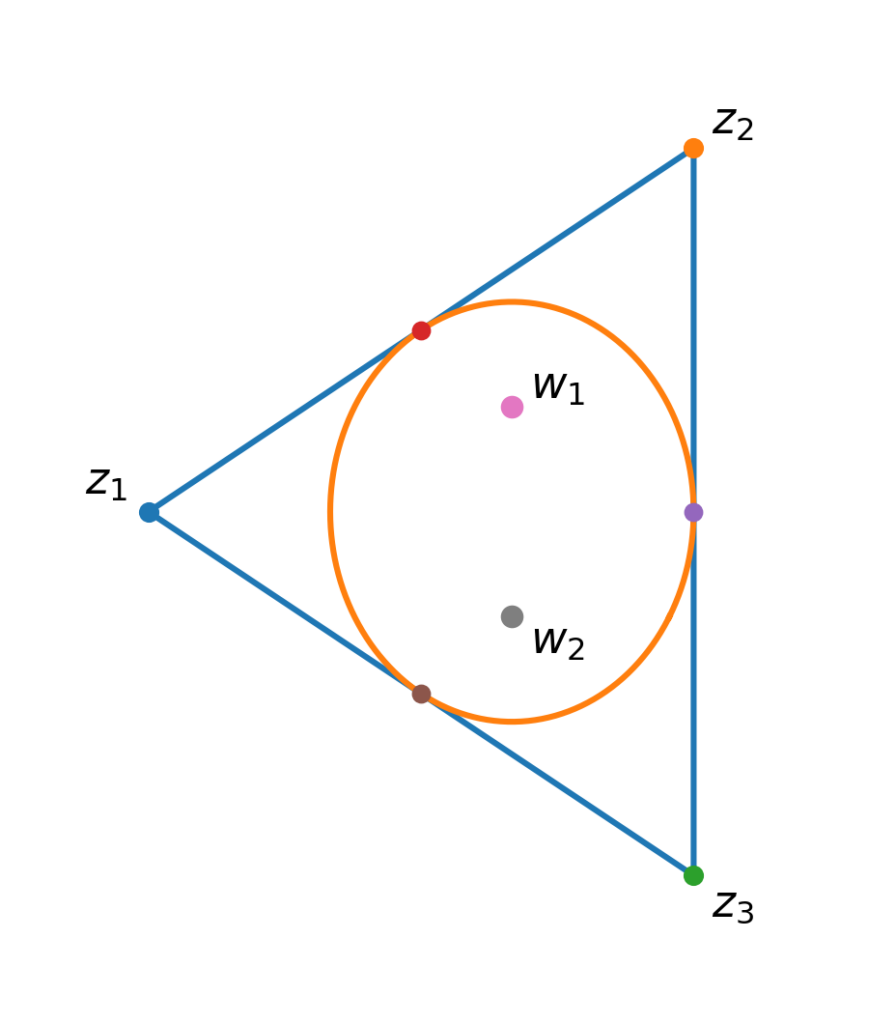
    Triangle formed by three complex roots with its Steiner inellipse tangent at the side midpoints. The two zeros of the derivative are marked at the two foci of the ellipse.
    Figure 3. Marden’s theorem: the two zeros w₁ and w₂ of the derivative are exactly the foci of the Steiner inellipse of the triangle formed by z₁, z₂, and z₃.

    A concrete example

    Let us see the theorem in action. Choose the three roots

    z1=−2, z2=1+2i, z3=1−2i.

    The corresponding cubic is

    p(z) = (z+2) (z−1−2i) (z−1+2i).

    Multiplying the conjugate factors first gives

    (z−1−2i) (z−1+2i) = z2 −2z +5.

    Hence

    p(z) = (z+2) ( z2 −2z +5 ) = z3 +z +10.

    Now differentiate:

    p′(z) = 3z2 +1.

    The critical points satisfy

    3z2 +1 =0,

    so

    z = ± i 3 .

    Marden’s theorem now tells us something geometric that would be very difficult to guess merely by looking at the polynomial:

    The two foci of the Steiner inellipse are
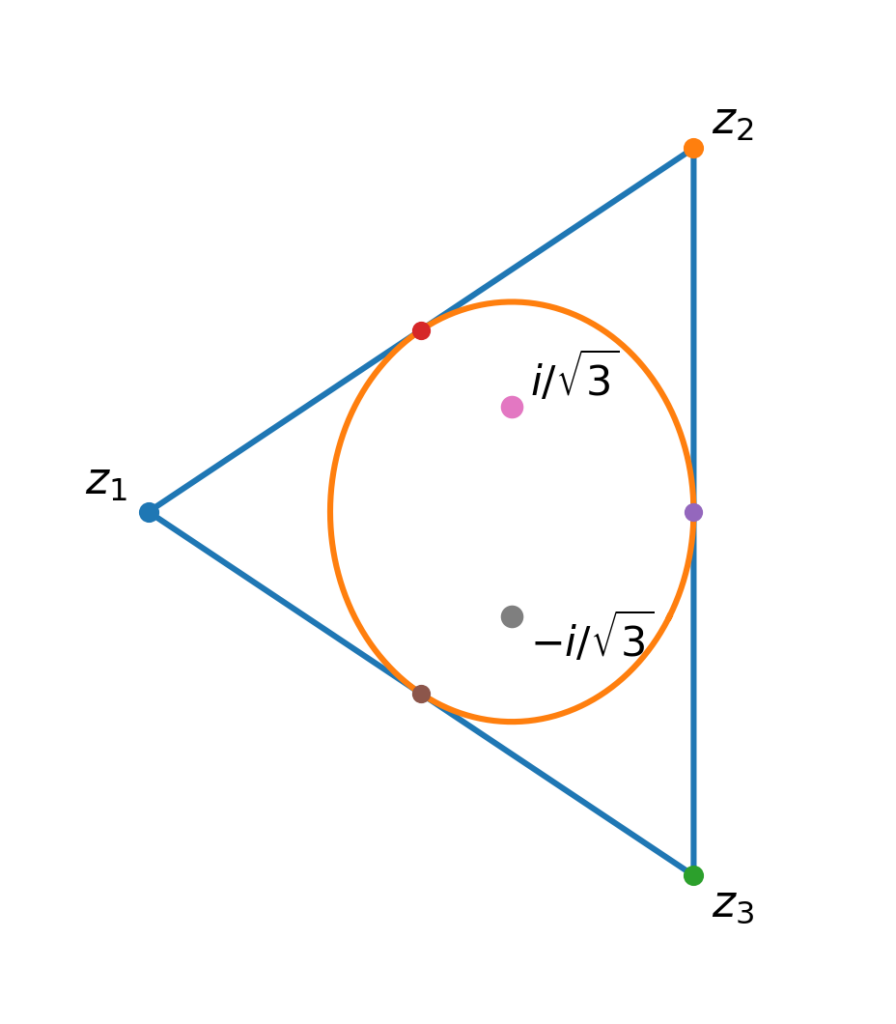
    i3 and − i3.
    Triangle with complex roots negative 2, 1 plus 2i, and 1 minus 2i, together with its Steiner inellipse. The two foci are located at i over square root of 3 and negative i over square root of 3.
    Figure 4. For p(z) = z³ + z + 10, the roots form the displayed triangle, while the zeros ±i/√3 of p′(z) are exactly the foci of its Steiner inellipse.

    Why is this so surprising?

    The derivative is usually introduced as an analytic object: it measures instantaneous rate of change, gives the slope of a tangent line, and locates critical points.

    Here it is doing something that looks completely different.

    Start with three complex numbers. Use them as the roots of a cubic. Differentiate the polynomial. Solve one quadratic equation. The two answers are not merely points somewhere inside the triangle—they are the two foci of a distinguished ellipse.

    In symbols, the chain of ideas is

    three roots → triangle → differentiate → two critical points → two foci.

    The same Steiner inellipse therefore admits two very different descriptions.

    In our earlier article, it appeared from an area condition: a point lies on the ellipse precisely when three corner triangles have total area equal to half the area of the original triangle.

    Here the ellipse appears from differentiation: its two foci are the zeros of the derivative of the cubic whose roots are the vertices of the triangle.

    This is a beautiful example of a recurring theme in mathematics: algebra, calculus, and geometry can encode the same object in completely different ways.

    References and further reading

    1. D. Kalman, “An Elementary Proof of Marden’s Theorem” , The American Mathematical Monthly, Vol. 115, No. 4 (2008), pp. 330–338.
    2. A. Eydelzon, “On a New Property of the Steiner Inellipse” , The American Mathematical Monthly, Vol. 127, No. 10 (2020), pp. 933–935.
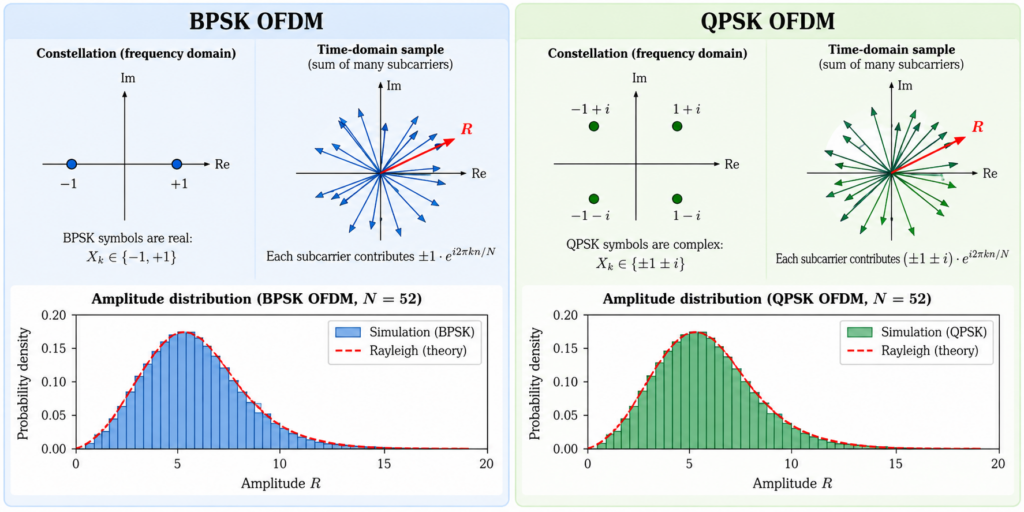
  • Why Does an OFDM Signal Have a Rayleigh Distribution?

    A complicated communication signal can sometimes be understood using surprisingly elementary mathematics.

    Consider a large number of vectors of length 1 pointing in random directions. Add them together. What can we say about the length of the resulting vector?

    This seemingly geometric probability problem leads directly to a standard mathematical model for OFDM (Orthogonal Frequency-Division Multiplexing), a technique used in modern digital communication.

    The path is beautiful:

    random phases → sine and cosine → Central Limit Theorem → two-dimensional Gaussian → Rayleigh distribution.

    Step 1: Add Random Unit Vectors

    Suppose that

    θ1 , θ2 , … , θN

    are independent random angles uniformly distributed between 0 and 2π .

    The corresponding unit complex numbers are

    e iθk = cos θk + i sin θk.

    Now add all of them:

    Z = ∑ k=1 N e iθk .

    Separating the real and imaginary parts gives

    Z = X + iY,

    where

    X = ∑ k=1 N cos θk , Y = ∑ k=1 N sin θk.

    Step 2: What Is the Distribution of One Coordinate?

    If θ is uniformly distributed on [0,2π] , then both sinθ and cosθ have density

    g (x) = 1 π 1−x2 , −1<x<1.

    This is sometimes called the arcsine distribution.

    By symmetry,

    E [cosθ] = E [sinθ] = 0.

    Also,

    E [ cosθ2 ] = E [ sinθ2 ] = 12.

    Therefore each coordinate has mean 0 and variance 12 .

    Step 3: The Central Limit Theorem Appears

    Now comes the key step.

    Both X and Y are sums of many independent random variables.

    When N is large, the Central Limit Theorem tells us that these sums are approximately normally distributed:

    X ≈ N ( 0 , N2 ) ,
    Y ≈ N ( 0 , N2 ) .

    In other words, the endpoint of our random walk is approximately described by a two-dimensional Gaussian distribution centered at the origin.

    Step 4: How Far Are We from the Origin?

    The amplitude of the complex sum is

    R = |Z| = X2 + Y2 .

    So we have reached a purely geometric question:

    If a point has two independent Gaussian coordinates, what is the distribution of its distance from the origin?

    The answer is the Rayleigh distribution.

    Since each coordinate has variance N2 , the approximate density of R is

    f (r) ≈ 2r N exp ( − r2 N ) , r≥0.

    This formula is important to interpret correctly. For a finite number of random unit vectors it is generally not the exact distribution. It is the large- N approximation produced by the Central Limit Theorem.

    A Shorter Derivation of the Rayleigh Formula

    There is also a beautiful geometric way to obtain the density.

    For large N, the joint density of (X,Y) is approximately

    p (x,y) = 1πN exp ( − x2 + y2 N ) .

    This density depends only on the distance from the origin.

    A thin circular ring of radius r and thickness dr has area approximately

    2πrdr.

    Multiplying the two-dimensional density by this ring area gives

    1πN exp ( − r2N ) · 2πrdr.

    Therefore,

    f (r) = 2rN exp ( − r2N ) .

    So the factor r in the Rayleigh distribution has a simple geometric origin: circles become longer as their radius increases.

    What Does This Have to Do with OFDM?

    An OFDM time-domain sample is produced by an inverse discrete Fourier transform. It therefore involves adding many complex contributions having different phases.

    This suggests viewing the sample, in a simplified model, as a sum of many complex vectors.

    That brings us back to exactly the random-vector problem above.

    An Example with 52 Active Carriers

    Consider a system with 64 available carrier positions, of which 52 are nonzero: 48 data carriers and 4 pilot carriers.

    The simple random-phasor model therefore suggests taking

    N=52.

    For a Rayleigh distribution with the density derived above, the expected amplitude is

    E[R] = πN 2 .

    For N=52 , this gives

    E[R] = 52π 2 ≈ 6.3907.

    How Good Is the Approximation?

    I originally investigated this question numerically by comparing the simple theoretical model with simulated OFDM signals.

    The theoretical mean amplitude for the 52-vector model is approximately 6.3907.

    A direct simulation of the random-vector model produced 6.3796.

    The corresponding simulated OFDM mean amplitudes were:

    Model Mean amplitude
    Rayleigh theory 6.3907
    Random-vector simulation 6.3796
    BPSK OFDM 6.3889
    QPSK OFDM 6.4015
    16QAM OFDM 6.4058
    64QAM OFDM 6.3837

    The agreement is remarkably good.

    A complicated digital communication signal has, at least at the level of its typical amplitude, been captured by a very simple model: add 52 vectors pointing in random directions.

    But What About Rare Peaks?

    Matching the average is not the whole story.

    For communication systems, unusually large signal peaks are important. An amplifier must be able to accommodate those peaks without severe distortion.

    This is where the difference between an approximation and an exact distribution becomes important.

    In the original numerical experiment, the simple theory tracked several OFDM simulations quite well at moderate thresholds. But differences appeared in the far tail of the distribution, particularly for BPSK.

    For example, at a peak-to-average threshold of 12 dB, the values from that simulation were approximately

    Model Tail probability
    Simple theory 4.0 × 10⁻⁶
    BPSK 1.969 × 10⁻³
    QPSK 9.4 × 10⁻⁵
    16QAM 7.9 × 10⁻⁵
    64QAM 4.0 × 10⁻⁵

    This illustrates an important lesson in probability.

    Two distributions can look very similar around their typical values while behaving quite differently in their extreme tails.

    The Central Limit Theorem explains the center of the distribution extremely well, but rare events can require more careful analysis.

    The Mathematics Behind a Communication Signal

    What I like about this example is the number of mathematical ideas that meet in one problem.

    We started with complex numbers:

    eiθ = cosθ + isinθ.

    Those became random vectors in the plane.

    Their coordinates led to probability distributions.

    Adding many of them brought in the Central Limit Theorem.

    The resulting two-dimensional Gaussian led, through elementary geometry, to the Rayleigh distribution:

    f (r) ≈ 2rN exp ( − r2N ) .

    And that simple formula gives a surprisingly accurate description of the amplitude of an OFDM signal.

    This is a good example of why mathematical modeling is so useful: the real system may be complicated, but sometimes the right simplified model exposes the mathematics underneath it.


    Where the Gaussian Function Enters the Story

    The Rayleigh distribution in OFDM is closely connected to Gaussian random variables. When many independent contributions combine, the in-phase and quadrature components of the signal are approximately Gaussian, and their magnitude produces the Rayleigh distribution.

    At the heart of the Gaussian distribution is the remarkable function e − x 2 . Its integral over the real line cannot be evaluated by finding an ordinary elementary antiderivative. Yet there is a beautiful way to compute it by moving from one dimension to two.

    Continue exploring: The Gaussian Integral and Beyond: From e^(-x²) to a Family of Integrals

  • A Sum of Cosines Is a Geometric Series—Could You Believe It?

    Consider the innocent-looking sum

    S = cosx + cos2x + cos3x + ⋯ + cosnx.

    At first glance, there is nothing geometric about it. The terms are cosines, not powers of a common ratio.

    But there is a geometric series hiding inside.

    The Key Idea

    Euler’s formula says

    eix = cosx + isinx.

    Therefore, the real part of eikx is coskx. Hence

    S = Re ( eix + e2ix + e3ix + ⋯ + enix ) .

    Now look carefully at the expression inside the parentheses. It is a geometric series!

    Its first term is eix, and its common ratio is also eix.

    Sum the Geometric Series

    Using the finite geometric-series formula,

    eix + e2ix + ⋯ + enix = eix 1 − enix 1 − eix .

    This already proves that our trigonometric sum comes from a geometric series. But we can simplify it further.

    A Useful Identity

    For any real number t,

    1 − eit = −2i eit/2 sin ( t2 ) .

    Apply this identity to both the numerator and denominator. After cancellation, we obtain

    eix + e2ix + ⋯ + enix = sin ( nx2 ) sin ( x2 ) e i (n+1)x 2 .

    Now take the real part. Since the real part of eiθ is cosθ, we arrive at

    cosx + cos2x + ⋯ + cosnx = sin ( nx2 ) cos ( (n+1)x 2 ) sin ( x2 ) .

    So the final formula is

    cosx + cos2x + ⋯ + cosnx = sin ( nx2 ) cos ( (n+1)x 2 ) sin ( x2 ) .

    This formula applies whenever sin(x/2)≠0. If x is a multiple of 2π, every cosine equals 1, so the original sum is simply n.

    There Is Geometry Behind the Geometric Series

    The connection is even more interesting than the algebra suggests.

    Each complex number

    eikx = coskx + isinkx

    can be viewed as a vector of length 1 making an angle kx with the positive horizontal axis.

    Thus the vectors

    eix , e2ix , e3ix , … , enix

    all have the same length, and each successive vector is obtained by rotating the previous one through exactly the same angle x.

    Place these vectors head-to-tail. They form a turning polygonal chain. Their vector sum is

    eix + e2ix + ⋯ + enix.

    And what is the horizontal component of this vector?

    Exactly

    cosx + cos2x + ⋯ + cosnx.

    So our sum of cosines really does have a geometric meaning.

    And the Sines Come for Free

    The imaginary part of exactly the same geometric series gives another classical identity:

    sinx + sin2x + ⋯ + sinnx = sin ( nx2 ) sin ( (n+1)x 2 ) sin ( x2 ) .

    One geometric series has given us two trigonometric identities.

    The Takeaway

    A sum such as

    cosx + cos2x + ⋯ + cosnx

    does not look remotely like a geometric series.

    But complex numbers reveal what is hidden:

    trigonometric sum → complex exponentials → geometric series → closed formula.

    Sometimes the hardest part of a problem is not doing the calculation. It is recognizing what the calculation really is.


    Another Unexpected Side of Trigonometry

    Writing a sum of cosines as part of a geometric series reveals algebra hidden inside trigonometry. There is another beautiful example of this idea in the historical problem of actually computing sines and cosines.

    Long before electronic calculators, Newton developed infinite series that turned sin ⁡ (x) and cos ⁡ (x) into expressions that could be evaluated using arithmetic.

    Continue exploring: How Newton Computed Sines and Cosines Without a Calculator